How to Transfer a Credit Card Balance (and When It's Worth It)

Credit cards have some of the highest interest rates of any type of debt. With such high interest rates, if you can’t pay off your balance in full one month, it’s easy for your balance to get out of hand. That’s why many people consider credit card balance transfers.
So what is a balance transfer credit card? This is when you transfer what you owe on one credit card to another with a lower interest rate. The idea is that the new, lower interest rate will reduce your monthly credit card payments so they're more affordable and you’re in a better position to chip away at your debt. The process works for debt on a personal loan or business credit card.
People don’t just use credit card balance transfers to take advantage of lower interest rates. They can also help you move to a credit card with better terms or consolidate your credit card debt from multiple cards so you have fewer payments to manage.
To transfer a credit card balance, apply for a card with a 0% intro balance transfer APR, then give the new issuer your old card's account number and the amount you want to move. The new issuer pays off the old card, usually within 5 to 14 days, and adds a one-time fee of 3% to 5% of the amount moved. The 0% rate is a promotional rate with an end date, so the plan only works if you pay the balance down before it expires.
Pros and Cons of Balance Transfers: Are They Worth It?
If you’re wondering if you should transfer the balance on a credit card, it’s important to weigh the pros and cons before you commit.
Balance transfer pros and cons
Pros
Lower interest cost: If your current card carries a high annual percentage rate (APR), moving the balance cuts what you pay in interest on the money you borrow.
A 0% promotional window: Some balance transfer cards charge no interest at all for an introductory period, so every payment goes toward the debt itself.
Fewer payments to track: You can consolidate balances from several cards onto one, or move to a card with better terms.
Cons
A fee up front: Most cards charge a balance transfer fee, so moving the debt isn't free.
The rate jumps when the promo ends: It's easy to focus on the intro rate and get caught by the much higher regular APR once the promotional period is over.
New spending undercuts the plan: Purchases you put on the card while paying down the balance start racking up interest, which makes the debt harder to clear.
How to Transfer a Credit Card Balance, Step by Step
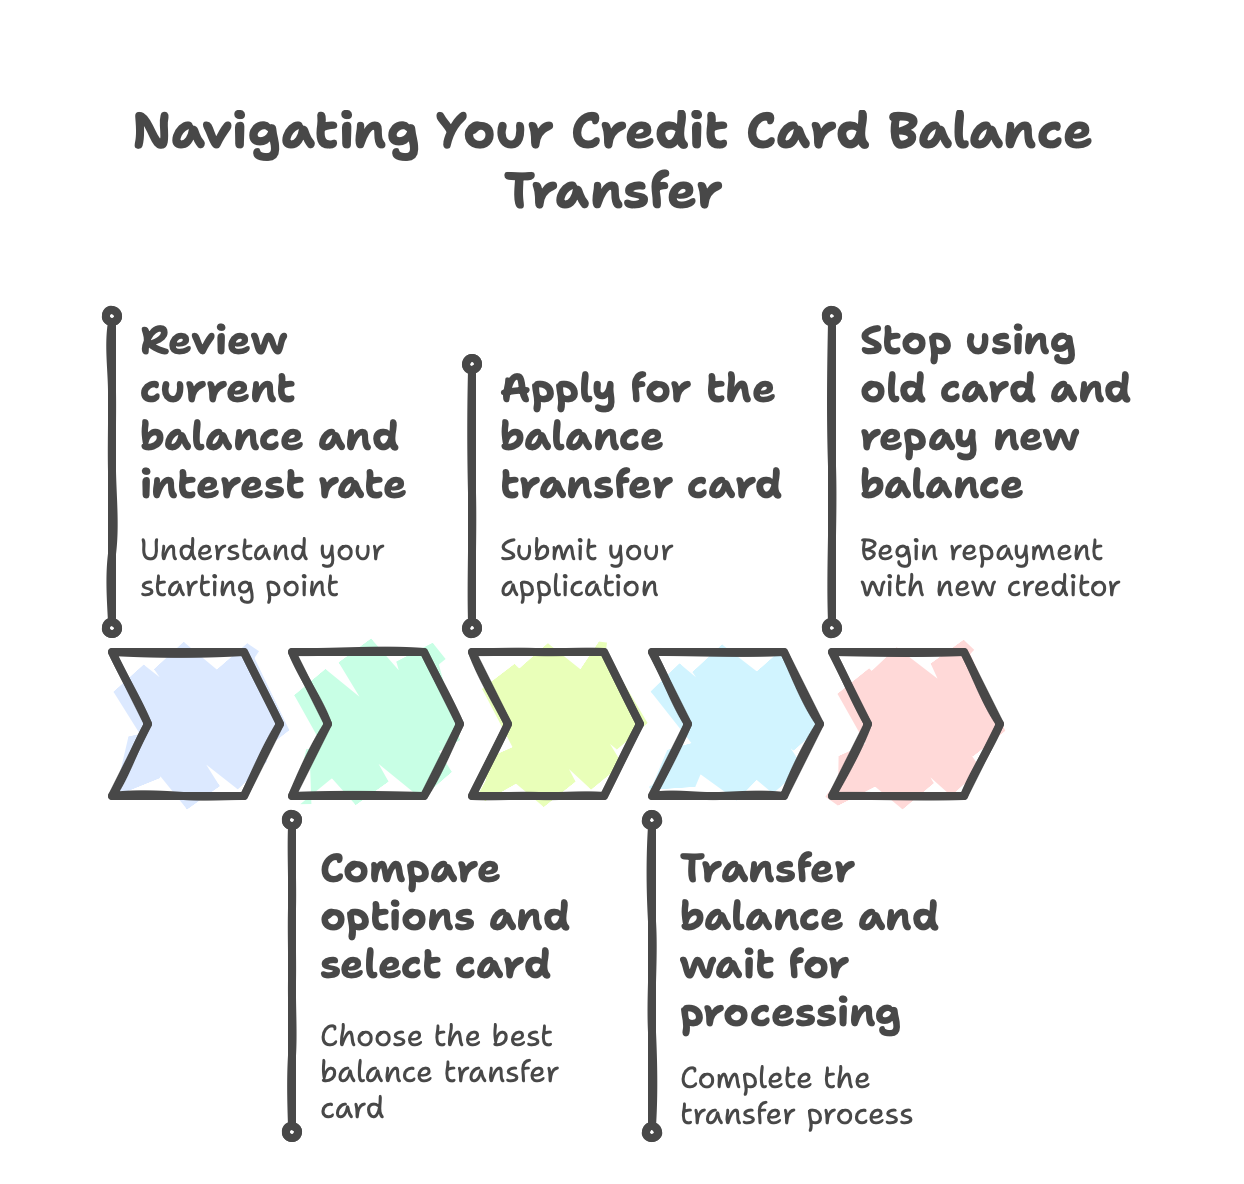
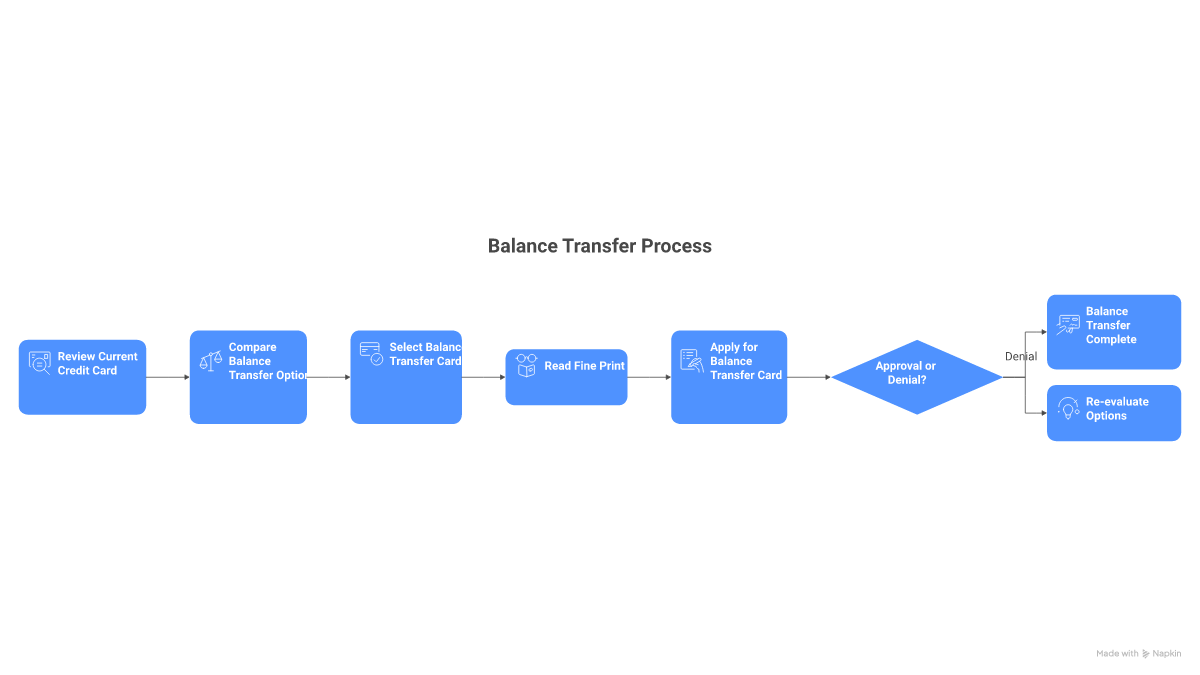
Here's how a balance transfer works from start to finish. Most of the elapsed time is spent waiting, first for approval and then for the transfer to post.
How to transfer a credit card balance
- 1
Total up your balances and APRs
List every card you want to pay down with its balance and current APR. That tells you how much you need to move and what the debt is costing you today.
- 2
Check your credit score
The longest 0% offers usually go to applicants with good to excellent credit. Knowing your score first tells you which cards are realistic, so you don't spend a hard inquiry on one you won't get.
- 3
Compare 0% intro balance transfer offers
Look at three numbers: how long the intro period lasts, the transfer fee, and the regular APR after the promo ends. Also check whether the card caps how much you can transfer. Start with our list of balance transfer credit cards.
- 4
Apply and request the transfer
Once approved, give the new issuer your old card's account number and the amount to move (many let you do this on the application itself). The issuer either pays the old card directly or sends you a balance transfer check. You generally can't move a balance between two cards from the same bank.
- 5
Keep paying the old card until the transfer posts
Transfers usually take 5 to 14 days and sometimes longer. Make at least the minimum payment on the old card until its balance shows as paid, or you risk a late fee.
- 6
Set a payoff plan
Divide the transferred balance, plus the fee, by the number of months in the intro period. That's your monthly target. Then stop using the old card for new purchases.
How Much Does a Balance Transfer Cost?
The direct cost is the balance transfer fee, usually 3% to 5% of the amount you move. You don't pay it out of pocket: it's added to the new card's balance, so a $5,000 transfer with a 3% fee starts life as a $5,150 balance.
Whether the fee is worth paying depends on the interest you'd otherwise owe. The table assumes you pay the balance off in equal monthly payments over 15 months, either at a 0% intro rate on the new card or at a 24% APR on your current one.
So the fee on a $1,000 transfer runs $30 to $50, and the interest you avoid covers it within about three months. The math gets worse if you can't clear the balance before the promo ends, because whatever is left starts accruing interest at the card's regular rate. Our guide to how interest rates affect a balance transfer walks through that scenario, and it's worth taking a minute to calculate your card's interest on your current balance before you apply.
Does a Balance Transfer Hurt Your Credit Score?
A balance transfer can lower your score a little at first and then help it. Applying for the new card triggers a hard inquiry, which can shave a few points off for a while, and opening the account lowers the average age of your accounts.
The bigger effect usually runs the other way. A new credit line raises your total available credit, so your credit utilization ratio, the share of your limits you're using, tends to fall. Amounts owed make up about 30% of a FICO score, so that drop often outweighs the inquiry.
Keep the old card open once its balance is gone. Closing it removes its credit limit and pushes your utilization back up. If it charges an annual fee, ask the issuer about switching to a no-fee version before you cancel.
Tips To Maximize a Balance Transfer & Avoid Pitfalls
Completing a balance transfer can be a positive first step toward tackling your credit card debt, but there’s still more work to do. Try these tips to make the most progress with your debt during a balance transfer.
Pay Off Debt Before the Promotional Period Ends
The introductory rate on balance transfer cards won’t last forever. Once the promotional period ends, you’ll have a new, often much higher, interest rate to pay on your remaining debt.
Get around this issue by paying off your debt before the promotional period ends, or at least as much of it as possible. The less debt you have left when the new interest rate goes into effect, the better off you’ll be.
Avoid New Debt While Managing Existing Balances
Try to avoid adding to your debt balances while you’re tackling your existing credit card debt. Any additional purchases you charge to your card will just start racking up more interest fees, making it harder to clear your balance.
Should You Use a Balance Transfer To Pay Off Debt?
Balance transfers can help you consolidate debt and access lower interest rates, but they’re not all created equal. If you’re thinking about this option, review all the available cards to find the best one for your needs.
MoneyAtlas’s thorough comparisons of different credit cards based on interest rates, fees, and other terms can help. Explore credit card options to discover your ideal balance transfer card.
FAQ
Ready to pick a card?
Compare the cards our editors rate highest right now, side by side, with the fees and rewards that matter.
Compare the best credit cardsEducation
- Bachelor’s Degree in Economics, Ramapo College of New Jersey
Expertise
- Debt and Credit Management
- Budgeting and Money-Saving Strategies
- Financial Digital Security and Fraud Protection
Related Articles
The Fed just raised rates. Which of your debts will cost more?
The Fed made its first rate hike since 2023 on September 16. See which debts go up, which stay locked, and what the hike costs you each month.
Your credit card APR is going up. Here's what to do before your next statement
Learn how to lower credit card APR with 5 proven strategies. From negotiating with issuers to 0% transfers, discover how to offset rising interest rates.
Does Credit Card APR Go Down? How to Lower Your Interest Rate
Does credit card APR go down? Learn how market shifts, improved credit, or negotiation can lower your rate and save you money on interest today.