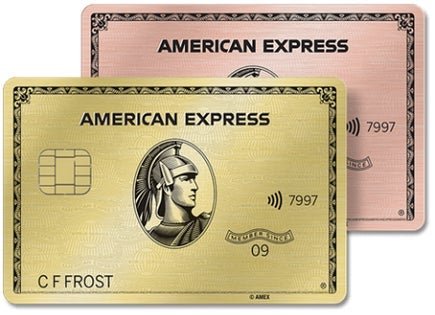
Whether you are looking to build a credit history or maintain a high score for a future mortgage, knowing how your card activity reaches the bureaus is essential. The American Express® Gold Card occupies a unique space in the financial world. It is often referred to as a charge card because it historically required payment in full each month and has no preset spending limit. Because of this specialized structure, many cardholders wonder if their activity is actually reported to the credit bureaus like a standard credit card.
MoneyAtlas tracks how major issuers handle data transmission to ensure you can manage your credit profile with precision. The short answer is yes: American Express reports the Gold Card to all three major credit bureaus. However, the way it affects your score, specifically your credit utilization, differs significantly from a traditional revolving credit card. This article explores the reporting timeline, the impact of the No Preset Spending Limit (NPSL) feature, and how to manage your Gold Card to strengthen your credit file.
Does the American Express Gold Card Report to Credit Bureaus?
American Express reports activity for the personal Gold Card to all three primary consumer credit bureaus: Experian, Equifax, and TransUnion. This means that your payment history, account age, and balance information will appear on your consumer credit reports. Consistent on-time payments on this card can help build a positive credit history, which is a primary factor in most credit scoring models.
It is important to distinguish between the personal version of the card and the business version. While the personal American Express Gold Card reports to consumer bureaus monthly, the American Express® Business Gold Card generally does not. Business card activity typically only appears on your personal credit report if the account becomes seriously delinquent, usually 60 days or more past due. For standard monthly use, the Business Gold Card helps build a business credit profile rather than a personal one.
Understanding the timing of when data moves from American Express to the bureaus can help you time your payments for maximum credit score benefit. Most issuers, including American Express, do not report activity in real time. Instead, they send a data "snapshot" once per billing cycle.
When Data Transmission Occurs
American Express typically transmits account data to the bureaus approximately 2 to 3 business days after your statement closing date. The balance that appears on your credit report is almost always the balance that was listed on your most recent statement. If you make a large purchase and pay it off before the statement closes, that high balance may never appear on your credit report. Conversely, if you wait until after the statement closes to pay, that full balance will likely be visible to lenders for the next 30 days.
How Long Until It Appears?
Once American Express sends the data, it may take another few days for the credit bureaus to process the update and reflect it on your credit report. If you are monitoring your score through a third-party tool, you might see the update within 5 to 7 days after your statement ends. For more context on billing cycles and statement timing, read our guide to when credit card interest is charged.
Event
Typical Timing
Statement Closing Date
The final day of your monthly billing cycle.
Data Sent to Bureaus
2 to 3 business days after statement close.
Report Reflects Update
5 to 10 days after statement close.
Payment Due Date
Usually 25 days after the statement close.
How the Gold Card Affects Your Credit Utilization
The most significant difference between the Gold Card and a standard credit card is how it influences your credit utilization ratio. Credit utilization is the percentage of your available credit limits that you are currently using. In traditional scoring models, keeping this number below 30% is often suggested for a healthy score.
No Preset Spending Limit (NPSL)
The American Express Gold Card is an NPSL card. This does not mean you have unlimited spending power. Instead, your limit is flexible and adjusts based on your usage patterns, payment history, and financial resources. Because there is no "hard" credit limit reported to the bureaus, many credit scoring models cannot calculate a utilization percentage for the card.
FICO vs. VantageScore Handling
Different scoring models treat NPSL cards differently:
FICO Scores: Most FICO models exclude NPSL cards from the revolving utilization calculation. This means a high balance on your Gold Card likely will not tank your score by making you look "maxed out," as there is no limit to be maxed out against.
VantageScore: Some versions of VantageScore may use your "highest ever balance" on the card as a proxy for a credit limit. In this scenario, a high balance could theoretically impact your score more than it would under FICO.
The Pay Over Time Factor
Many modern Gold Cards come with a "Pay Over Time" feature. This allows cardholders to carry a balance on eligible purchases with interest, similar to a traditional credit card. When you use this feature, the card behaves more like a revolving account. MoneyAtlas helps you compare how different card structures impact your long-term credit goals by reviewing top-rated credit card options side by side.
Strategic Management of Your Reported Balance
Since the balance reported is your statement balance, you have some control over what lenders see. Even though the Gold Card may not count toward utilization in the same way as other cards, a very high reported balance can still affect your debt-to-income (DTI) ratio when applying for a mortgage or auto loan.
The Pre-Statement Payment Strategy
If you have a large expense on your Gold Card, such as a vacation or a business expense, you can prevent that high balance from appearing on your report. By paying the balance down a few days before your statement closing date, you ensure that the "snapshot" sent to the bureaus reflects a lower number. Our guide to how APR timing works on a credit card offers additional context on statement timing and payments.
Monitoring for Accuracy
Checking your report regularly ensures that American Express is reporting your on-time payments correctly. You can access your reports from all three bureaus through various free tools or the official annual credit report site. Look specifically for the "account status" and "payment history" sections to confirm there are no erroneous late marks.
The Impact of Late Payments
While the Gold Card offers flexibility, the reporting of negative information is strict. American Express generally follows the standard industry timeline for reporting late payments.
Missed Due Date: If you miss your payment due date, you will likely be charged a late fee. However, American Express usually does not report the late payment to the bureaus immediately.
30 Days Past Due: A payment is typically only reported as "late" to the credit bureaus once it is a full 30 days past the due date.
The Impact: Once a 30-day late mark hits your report, it can stay there for up to 7 years. This is one of the most damaging events for a credit score.
60+ Days Delinquency: For business cardholders, this is often the point where the activity may begin to appear on a personal credit report, negating the benefit of keeping business and personal credit separate.
To avoid these risks, cardholders often use autopay. If you are facing financial hardship, contacting the issuer before the 30-day window closes is a practical step. They may offer relief programs that can prevent a late mark from being reported.
How to Find Your Specific Reporting Date
Since reporting is tied to your statement closing date, finding that date is the first step in managing your credit profile. You can locate this information in a few ways:
Online Portal: Log into your American Express account and look at the "Statements & Activity" tab. The "Statement Closing Date" will be clearly listed for your current and past cycles.
Mobile App: Under the "Account" or "Statements" section of the Amex app, you can view the closing date of your current billing period.
Paper Statements: The closing date is usually located on the first page, near the top right or within the account summary box.
Your statement closing date usually stays the same each month, but it can shift by a day or two due to weekends or the length of the month, especially in February.
Comparing Amex Gold Reporting to Other Cards
When deciding which card to use for a large purchase, it helps to understand the reporting trade-offs. MoneyAtlas makes it easier to compare side by side how different cards might impact your credit.
If you use a traditional credit card with a $5,000 limit and charge $4,500, your credit report will show 90% utilization for that card. This could significantly drop your credit score. If you put that same $4,500 on an American Express Gold Card, it likely will not count toward your utilization ratio in FICO models. For someone planning to apply for other credit soon, using the Gold Card for large purchases can be a strategic move to keep their reported utilization low on other revolving accounts. Readers comparing debt-payoff alternatives can also review balance transfer card options.
Summary of Credit Reporting Facts
Managing an American Express Gold Card requires a different mindset than a standard credit card. Because it is built on a charge card framework, the rules of the road for credit reporting are specialized.
Checklist for Success
Confirm your statement closing date each month.
Aim to pay your balance in full by the due date to avoid interest and late fees.
Make payments 3 or 4 days before the statement close if you want a lower balance reported.
Check your credit reports monthly to ensure your payment history is being recorded accurately.
Keep in mind that the Business Gold Card activity stays off your personal report unless you default.
Conclusion
The American Express Gold Card is a powerful tool for building credit history through consistent payment reporting, but its impact on your credit utilization is unique. By reporting to Experian, TransUnion, and Equifax, it ensures your responsible habits are visible to future lenders. However, because it often operates outside the traditional utilization math, it provides a level of protection against score dips caused by high balances.
Understanding these mechanics allows you to use the card strategically. Whether you are using the Pay Over Time feature or paying in full every month, the data transmitted shortly after your statement close date defines your credit profile for that month. For those looking to optimize their financial toolkit, comparing how different card types report is a smart move. You can compare credit cards to see how other cards in the American Express portfolio or competing issuers handle credit reporting and limits.
FAQ
Ready to pick a card?
Compare the cards our editors rate highest right now, side by side, with the fees and rewards that matter.
Wondering what is the difference between American Express Gold and Platinum? Compare annual fees, 4X vs 5X rewards, and luxury travel perks to find your fit.