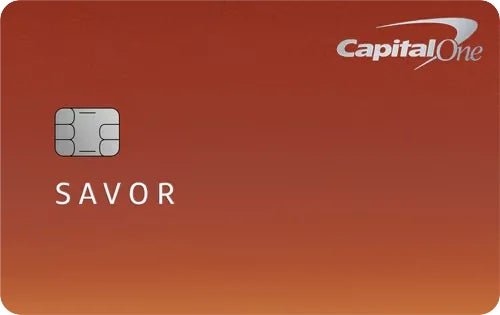
Capital One Savor Cash Rewards Credit Card
High cash back on dining and entertainment spending
Updated October 20, 2026 · By the MoneyAtlas Editorial Team
Pros
Dining & entertainment rewards: Earn 3% cash back on dining, entertainment, popular streaming services, and grocery stores
No annual fee: Maximize your rewards earnings without an offsetting cost
Flexible redemption: Cash back can be redeemed as statement credits, checks, or to cover recent purchases with no minimum redemption amount.
Cons
Limited base rewards rate: Only 1% cash back on purchases outside of bonus categories
Potentially high APR: Variable APR can be high for those with a balance after the intro period
Requires good to excellent credit: May not be accessible to all applicants.
Why we rate it 4.8/5
A no-annual-fee card that pays 3% where most households actually spend, held back by a 1% rate on everything else.
Unlimited 3% back on dining, entertainment, popular streaming and grocery stores covers a lot of everyday spending. Everything outside those categories earns 1%, and superstores such as Walmart and Target do not count as grocery stores.
There is no annual fee, so every dollar of cash back is net gain and the card costs nothing to keep open in a slow spending year.
No foreign transaction fees is the most useful extra. Beyond that the benefits list is short next to cards that charge a fee, so do not pick it for protections or travel perks.
No rotating categories, no activation and no caps. Cash back does not expire while the account is open and can be redeemed in any amount.
The Capital One Savor Cash Rewards Credit Card offers an attractive cash back program with no annual fee, making it a popular choice for those who enjoy dining out, entertainment, and grocery shopping. This card combines generous rewards in popular spending categories with flexible redemption options.
Savor vs. SavorOne: What Changed
If you remember this card as the SavorOne, you are not misremembering. Capital One used to sell two versions: a Savor with an annual fee and a no-annual-fee SavorOne. In 2024 it stopped taking applications for the fee version and moved the Savor name onto the no-fee card, which is the product this review covers. The rewards did not change with the name.
The confusing part is that the SavorOne name is back on a different card. Capital One now lists a SavorOne for applicants with fair credit, and that one charges an annual fee. Plenty of older reviews and search results still say SavorOne when they mean this card. Check for the annual fee before you apply: the Savor reviewed here has none, which keeps it among the no-annual-fee credit cards we track.
Capital One Savor Card at a Glance
- Annual Fee:
- Welcome Bonus:
- Rewards Rate:
- 3% cash back on dining, entertainment, popular streaming services, and at grocery stores
- 5% cash back on hotels and rental cars booked through Capital One Travel
- 8% cash back on Capital One Entertainment purchases
- 1% cash back on all other purchases
- Intro APR: then
- Foreign Transaction Fees: None
Capital One Savor Rewards: What You Earn and How to Redeem
The Savor card's rewards program is designed to cater to food and entertainment enthusiasts:
- Earning Cash Back: Cardholders earn 3% cash back on dining, entertainment, popular streaming services, and at grocery stores, with no caps or category restrictions
- Bonus Earning: 5% cash back on hotels and rental cars booked through Capital One Travel and 8% cash back on Capital One Entertainment purchases
- Redemption Options:
- Redeem for cash back as a statement credit or check
- Use rewards to cover recent purchases
- Redeem for gift cards or shop with rewards on Amazon.com
Cash back doesn't expire for the life of the account, and there's no minimum redemption amount.
Best Way to Use Capital One Savor Rewards
The Savor card earns its keep when it handles four jobs: restaurants and takeout, grocery store runs, streaming subscriptions, and tickets or other entertainment. Those all earn the 3% rate with no cap. Book hotels and rental cars through Capital One Travel when the price matches what you would pay elsewhere, because that tier pays more than the 3% categories.
Two habits cost people money. The first is buying groceries at a superstore such as Walmart or Target. Capital One excludes those from the grocery category, so the trip earns 1%. The second is using the Savor for everything else. Gas, utilities and general shopping also earn 1%, and a flat-rate card beats that. Pair the two and you cover both sides.
Redeeming Capital One Savor rewards takes no strategy. Cash back can be taken in any amount and does not expire while the account is open, so there is no reason to let a balance sit waiting for a threshold.
Travel Benefits
While not primarily a travel card, the Savor offers some travel-friendly features:
- No foreign transaction fees, making it suitable for international use
- Travel accident insurance
- 24-hour travel assistance services
Additional Perks
The card also includes some valuable shopping protections:
- Extended warranty protection on eligible purchases
- Virtual card numbers for safer online shopping
Downsides of the Capital One Savor Card
The downsides of the Capital One Savor card are narrow but real. Spending outside the bonus categories earns 1%, which is less than a flat-rate card pays on the same purchase. Superstores such as Walmart and Target do not count as grocery stores. Capital One lists the card for excellent credit, so approval is not a given. And it is a poor place to carry a balance once the intro period ends, because interest outruns 3% cash back quickly. If most of your spending falls outside food and entertainment, compare cash back credit cards before you settle on this one.
Who Should Get the Capital One Savor Card?
The Capital One Savor Cash Rewards Credit Card is ideal for:
- Those who frequently dine out or order in
- Entertainment enthusiasts who enjoy movies, concerts, and sporting events
- Consumers who spend significantly on grocery shopping and streaming services
- People who want to earn cash back without paying an annual fee
How to Get the Capital One Savor Card
Capital One lists the credit level for the Savor as excellent. It does not publish a minimum Capital One Savor credit score or a minimum income for the card, and anyone who quotes you one is guessing.
Start with Capital One’s preapproval tool. It asks for basics such as your income and date of birth and runs a soft inquiry, which does not affect your credit score. Preapproval is not a guarantee. Accepting an offer triggers a hard inquiry, and Capital One may ask you to verify what you entered.
Income matters because of federal rules, not issuer preference. Under Regulation Z, a card issuer has to consider your ability to make the required payments before it opens an account, which is why the application asks about income and what you already owe.
Capital One also limits how often it approves the same person. Its preapproval page says you may be ineligible if you were recently approved for another Capital One card or applied two or more times in the past 30 days. If you are not preapproved, our best credit cards page lists options across credit levels. The full terms for the card sit in the agreement Capital One files with the CFPB’s credit card agreement database.
Compare


Capital One Savor vs. Quicksilver
Both cards come from the same issuer and neither charges an annual fee. The choice comes down to where your money goes.
The break-even is simple. Every dollar in the 3% categories earns twice what Quicksilver pays, and every dollar outside them earns a third less. If food, streaming and entertainment make up more than about a quarter of your card spending, the Savor comes out ahead. Our Capital One Quicksilver review has the full breakdown, and students should look at the Savor Student card instead.
Bottom Line
The Savor card offers a compelling rewards rate in popular spending categories, with no annual fee. Its combination of dining, entertainment, and grocery rewards makes it a versatile choice for everyday use. The added travel benefits and shopping protections enhance its value, making it an attractive option for many consumers.
While it may not offer the highest overall cash-back rate, its targeted bonus categories and user-friendly redemption options make it a strong contender in the cash-back credit card space. It's particularly well-suited for those who want to maximize their rewards on food and entertainment expenses without the complexity of rotating categories or the cost of an annual fee.